

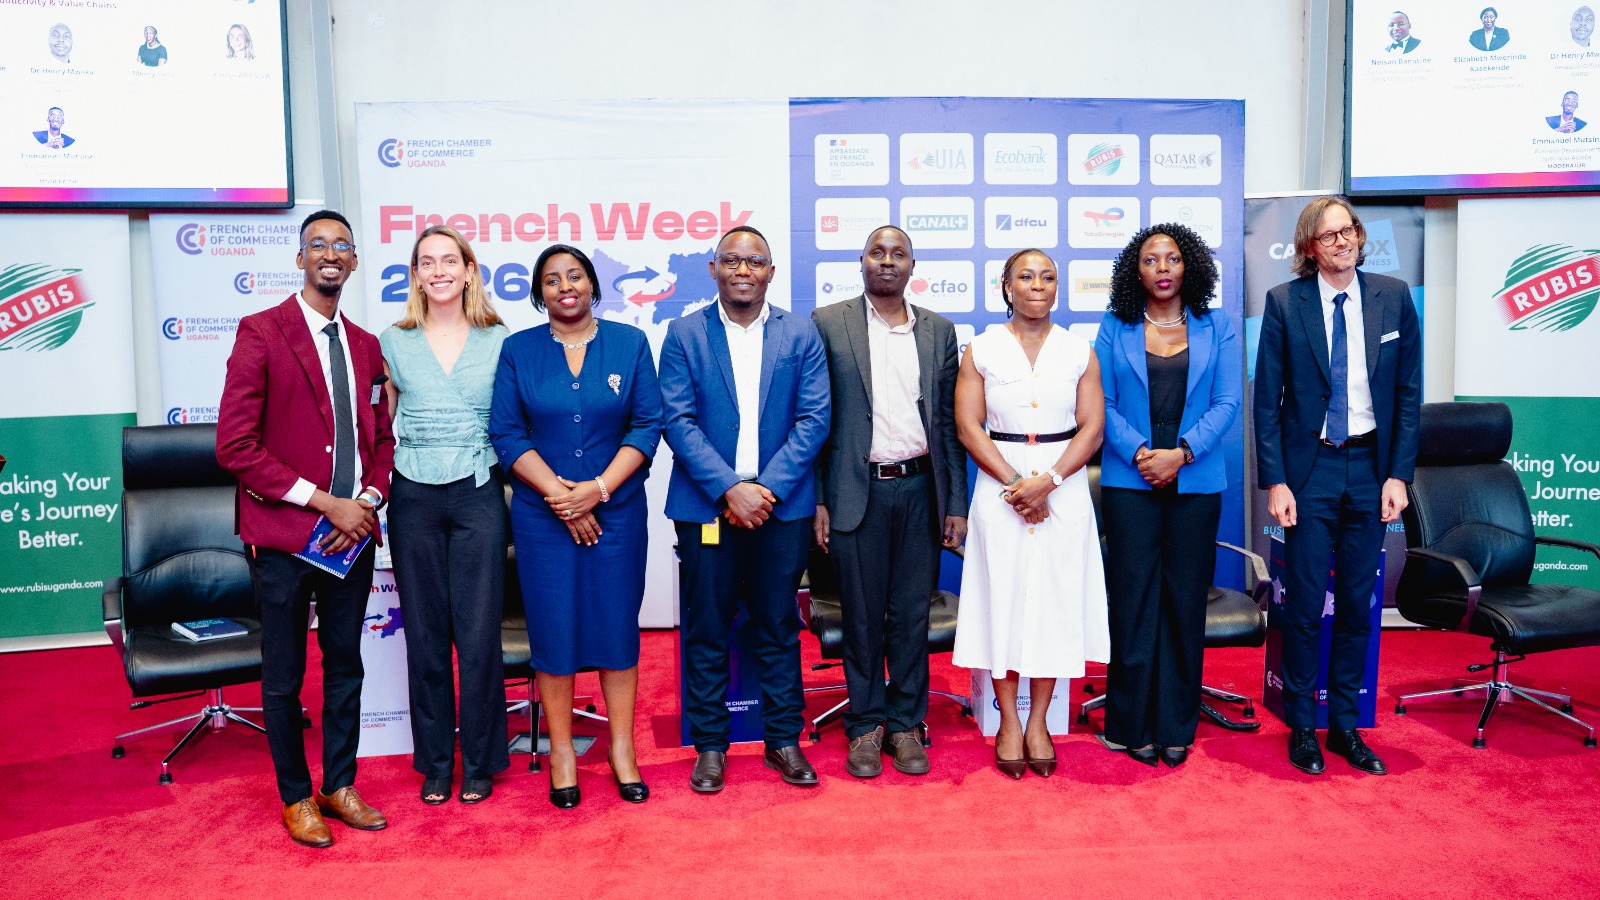
KAMPALA, Uganda: 23 September 2026 — As Uganda accelerates efforts to commercialise its agricultural sector, emerging technology is giving financial institutions deeper visibility into farming businesses and opening up new avenues for credit access.
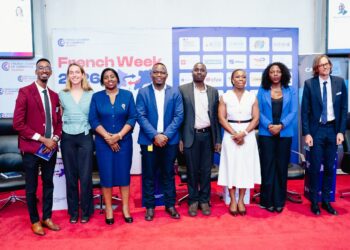
Speaking at the French Week Business Forum at the Uganda Business Facilitation Centre, Mercy Iselu, Sector Head for Food and Agriculture at dfcu Bank, noted that technological advances allow banks to track production cycles, cash flows, and overall operational performance with unprecedented precision.
She explained that digital transaction histories and real-time data sources enable lenders to make informed credit decisions grounded in verifiable business activity, rather than relying on sparse historical records.
“If the bank is satisfied with the data available, it creates trust by providing verifiable evidence of a farmer’s income,” Iselu said. Better-quality data gives lenders a clear view of repayment capacity, allowing them to structure credit tailored to actual agricultural cycles.
This digital shift comes as Uganda addresses broader structural economic challenges. According to the 2024 National Population and Housing Census, 33.1% of households remain in the subsistence economy, while 66.9% participate in the money economy—underscoring the massive scale of commercialisation required to drive household incomes and national productivity.
However, Iselu cautioned that improved data alone is not a silver bullet. Current agricultural financing remains heavily skewed toward short-term, seasonal production, whereas sustainable commercial growth requires patient, long-term capital for infrastructure and equipment.
“Most of the financing available is based on the season. But if financial institutions want to transform the sector, there is a need for long-term financing,” she emphasized.
To transition from basic inputs to high-yield operations, farmers require capital for machinery, solar-powered equipment, irrigation systems, and post-harvest infrastructure. Unlocking this level of investment will require active collaboration across the value chain, bringing together banks, equipment vendors, technology providers, and agricultural insurers.
Furthermore, Iselu highlighted that digital advisory tools cannot bridge the funding gap in isolation. While farm-management apps can diagnose crop diseases and point out operational inefficiencies, many farmers still lack the affordable capital needed to take corrective action.
“The biggest disconnect is therefore affordability and access to finance,” she said.
Addressing the forum, Dr. Sam Mugume, Acting Commissioner for Macroeconomic Policy at the Ministry of Finance, Planning and Economic Development, reaffirmed that agriculture remains central to Uganda’s development strategy due to its vast impact on employment and rural livelihoods.
Dr. Mugume stressed that boosting farm productivity is vital to reaching the country’s long-term economic targets. While digital tools expand access to credit, he argued that targeted public investment in rural roads and irrigation works hand-in-hand with private finance to derisk agricultural lending.
He advocated for a strategic shift from financing individual farmers in isolation to funding integrated agricultural value chains. This holistic framework connects smallholders, aggregators, processors, equipment suppliers, insurers, and logistics providers under a single coordinated system.
Public funds, Dr. Mugume noted, should focus on building the enabling environment required to crowd in private capital—particularly for mechanisation and irrigation—while robust public-private partnerships address the systemic bottlenecks stifling output.
The panel concluded that while data-driven credit risk assessment offers a strong foundation, true structural transformation in Ugandan agriculture will require combining technology with affordable long-term capital, resilient infrastructure, and value-chain integration.